

Dollarbird Pro

- 128.00 Reviews
- 3.3
- Downloads
- 50,000+
Our take on Dollarbird Pro from Appgk
I find that personal finance apps usually fall into two camps: detailed trackers that ask you to manage every transaction, and simple budget tools that show a few totals without much context. Dollarbird Pro takes a different route. It treats money as something that happens across a calendar, so the main question becomes not only “How much do I have?” but also “What will my balance look like after the next bills and purchases?” That makes it an interesting choice for people who plan around paydays, rent, subscriptions, and irregular expenses.
After spending time with it, my impression is that this is best understood as a personal finance calendar rather than a complete banking replacement. It is free to download, rated for Everyone, and developed by Dollarbird Apps SRL. The app has reached over 50 thousand installs and holds a 3.3 average from more than 500 ratings, which suggests a useful but not universally smooth experience. I would not choose it simply because it promises an AI touch. I would choose it if I genuinely wanted to see my financial life laid out by date.
How to decide whether a calendar budget fits your life
The first decision is about how you naturally think about money. If you prefer categories, receipts, and detailed reports, a conventional expense tracker may feel more familiar. If you mainly need to know whether you can safely spend before the next payday, a calendar can be more practical. Dollarbird Pro is built around the second habit. Its usefulness depends on entering expected income and expenses consistently, then checking how those entries affect the days ahead.
That approach is particularly valuable when timing matters. Two people can have the same monthly income and very different levels of financial pressure if one has rent due immediately after payday and the other has several bills scattered across the month. A monthly total can hide that problem. A calendar view makes the gap visible, which is the strongest reason to consider this app over a basic notes document or a spreadsheet.
Best Parts of Dollarbird Pro
Things to Keep in Mind About Dollarbird Pro
I also think the app suits people with predictable recurring commitments. Rent, utilities, school costs, insurance, memberships, and loan payments are easier to understand when they appear in the same timeline as income. The calendar does not magically improve a budget, but it encourages a habit that many simple trackers miss: looking forward before spending.
There is a trade-off, though. A calendar is only as useful as the entries behind it. If you forget a cash purchase, delay recording a bill, or estimate an irregular expense too optimistically, the projected balance can give you false confidence. I would therefore treat Dollarbird Pro as a planning instrument, not an automatic source of truth. It rewards regular maintenance more than occasional checking.
News and Features Related to Dollarbird Pro

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The everyday scenario where it makes the most sense
Imagine I receive my salary near the end of the month, pay housing costs a few days later, and have smaller subscriptions and household bills spread throughout the following weeks. Before buying something nonessential, I can look at the calendar and see whether the purchase lands before or after those commitments. That is a more useful question than simply asking whether my account looks healthy today.
I would also use it before a weekend trip. I could enter the expected travel spending, keep the next bills visible, and see whether the plan creates a tight period before the next income arrives. The important insight is not the exact prediction; it is the timing of the pressure. This makes the app helpful for people who are paid monthly, freelancers who need to reserve money for future obligations, or households that regularly feel “fine now, short later.”
Don't want to read the full review?
For shared finances, the calendar can also serve as a conversation aid. Instead of arguing from memory about what is affordable, two people can review upcoming commitments together. I would still agree on who records which expenses, because a shared plan becomes unreliable quickly when both users assume the other person is updating it.
What I like about the calendar-first design
The biggest strength is that it changes the shape of the budgeting conversation. Many finance apps focus on looking backward: how much was spent on food, transport, or entertainment. Dollarbird Pro puts more attention on the next financial events. That is valuable for avoiding surprises, especially when several medium-sized payments arrive close together.
Screenshots
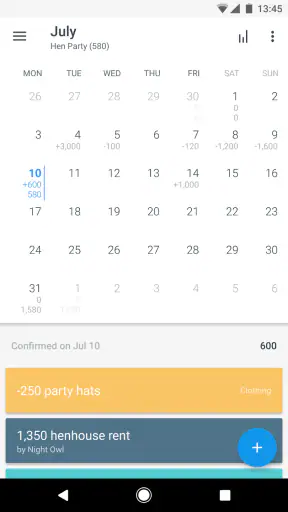
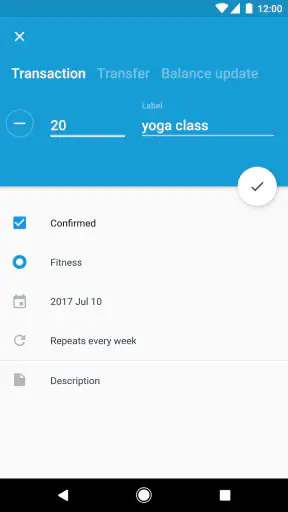
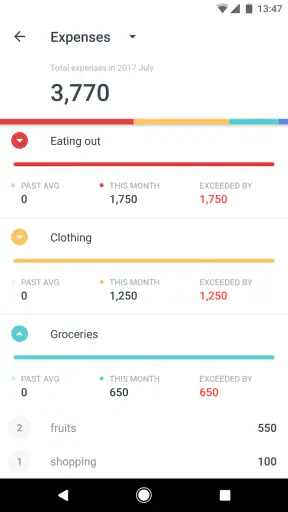
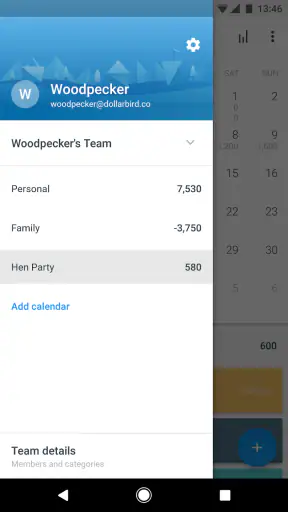
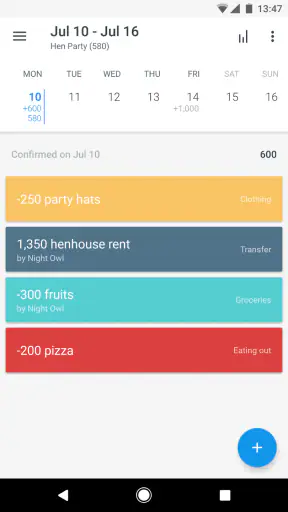
Another benefit is the lower mental barrier compared with a full spreadsheet. A spreadsheet can be extremely flexible, but it asks the user to design formulas, maintain layouts, and decide how to represent future transactions. A calendar-based app gives the process a clearer starting point. I can think in dates first and categories second, which feels closer to how bills actually affect daily life.
The AI element may appeal to users who want a little assistance rather than a completely manual ledger. I would keep expectations sensible, however. The app’s core value remains the calendar workflow. The AI spark is a supporting detail, not a reason to abandon careful checking. Any suggestion or interpretation should be treated as a prompt to review the plan, not as financial advice.
A less obvious advantage is that the calendar can expose “small” recurring costs that do not feel important individually. A subscription may be easy to ignore when viewed alone, but its placement alongside rent, utilities, and a planned purchase can change the decision. I find this more actionable than a report that merely says the subscription category increased.
Three habits that make the app more useful
My first recommendation is to enter future obligations before recording everyday spending. Start with income dates and fixed bills, then add flexible expenses. This creates a skeleton of the month and shows where the genuinely risky gaps are. If you begin with coffee and groceries but forget a large upcoming payment, the calendar looks detailed without being dependable.
Second, I would use conservative estimates for expenses that vary. When a bill normally falls somewhere within a range, entering the lower figure can make the projection look comfortable while hiding the possibility of a shortfall. A slightly cautious estimate is more useful because it gives me a reason to keep a buffer. Once the real amount is known, I can adjust the entry rather than pretending the original estimate was exact.
Third, I would review the calendar at a fixed weekly moment instead of opening it only when I am anxious about money. A short weekly check is enough to remove completed items, add unusual expenses, and look at the next pay cycle. This turns the app into a planning routine. Without that routine, even a well-designed calendar becomes another forgotten finance tool.
A fourth tactic is to separate predictable commitments from decisions I can still change. I would mark the items that are effectively locked in, then pay closer attention to discretionary plans around them. The point is not to make every expense feel restrictive. It is to identify which dates have no flexibility and which spending choices can move if the month becomes tighter than expected.
Where Dollarbird Pro wins, and where another category may fit better
Compared with a basic banking app, Dollarbird Pro is more forward-looking. A bank application is usually excellent for showing actual balances and completed transactions, but it may not present future commitments in a way that helps with planning. I would use the bank as the record of what really happened and Dollarbird as the calendar for what I expect to happen. That combination can work well, provided I accept the extra responsibility of keeping planned entries current.
Compared with a spreadsheet, the app is likely to feel less intimidating for someone who wants a ready-made personal finance structure. A spreadsheet wins when I need custom calculations, unusual household rules, or complete control over how data is organized. Dollarbird Pro wins when I want to open a calendar and immediately think about dates. The choice is less about which tool is more powerful and more about which one I will actually maintain.
Compared with category-heavy budgeting apps, this one is better suited to cash-flow awareness than detailed spending analysis. If my main goal is to discover exactly how much I spend on restaurants versus groceries, I would look for a tool designed around transaction categorization and reports. If my main concern is whether a bill arriving next week will collide with another obligation, the calendar structure is more directly relevant.
There is also a difference between manual planning and automatic financial aggregation. Users who expect accounts, transactions, and balances to update with minimal input may find this workflow too hands-on. I would not recommend it to someone who dislikes entering plans or checking them. The app’s advantage is precisely the act of deliberately mapping out the future, so that same requirement becomes its main limitation for people seeking automation.
Families and couples should think about coordination before committing. A shared calendar can be useful, but only if everyone agrees on whether entries represent confirmed payments, estimates, or personal spending. Without that agreement, one person may read a figure as money already reserved while another sees it as a rough guess. The app can support a shared planning habit, but it cannot create that household rule for you.
Questions I would ask before installing it
Will it work for someone with irregular income? Yes, but only with more active updating. A freelancer or commission-based worker can enter expected income as it becomes clearer and use the calendar to protect upcoming obligations. The projections will naturally be less stable than those of someone with a fixed salary, so I would keep a larger buffer and revisit the plan after every payment.
Is it suitable for someone who wants investment tracking or advanced financial analysis? I would look elsewhere if those are the main priorities. Dollarbird Pro makes sense as a day-to-day cash-flow planner. It should not be mistaken for a complete financial planning suite simply because it sits in the finance category.
Does the free version make it easy to try? The app itself is free, which lowers the barrier to testing the calendar approach. It also includes in-app purchases ranging from $7.99 to $79.99 per item, so I would inspect the available upgrade choices before treating it as a permanently cost-free solution. The sensible approach is to try the basic workflow first and decide whether the calendar actually changes my behavior before paying for anything.
What about device compatibility? The current version is 6.2.2 and requires Android 6.0 or later. That makes it accessible to many older Android devices, though I would still check how comfortably it runs on my particular phone before building a serious financial routine around it. A finance app needs to be convenient enough that opening it does not feel like a chore.
Is the average rating a reason to avoid it? Not automatically. The 3.3 average from over 500 ratings tells me that the experience is mixed, so I would approach it with realistic expectations rather than assume it will suit everyone. For me, the key question is whether the calendar method matches my needs. A moderate rating matters less when the app solves a specific problem I actually have, but it is a good reminder to test the workflow carefully.
The real cost of switching from a familiar budget tool
Moving to a calendar-based system has a setup cost that is easy to underestimate. The difficult part is not learning where to tap; it is deciding which future expenses deserve entries and how accurate those entries need to be. I would begin with one complete pay cycle rather than attempting to reconstruct every past purchase. That keeps the transition manageable and lets me judge the forward-planning benefit quickly.
I would also avoid duplicating every detail from an existing budgeting app on the first day. Importing a large history, if available in my current workflow, is less important than creating a reliable picture of upcoming income and fixed commitments. The purpose of switching is to improve decisions about the future. Historical detail can be added gradually if it helps, but it should not become a barrier.
There is a behavioral cost too. A category-based tracker may encourage me to review spending after it happens, while Dollarbird Pro asks me to make predictions before it happens. That can feel less satisfying at first because the calendar is full of estimates and intentions. Over time, however, those estimates become useful feedback: I can compare what I expected with what actually occurred and improve the next cycle.
My practical transition plan would be simple. I would keep the old tool available for reference, enter the next income date and unavoidable bills into the calendar, then record only the flexible expenses that could affect the balance. After a few weeks, I would know whether seeing those dates changed my choices. If it did not, switching fully would probably add maintenance without enough benefit.
Who should choose it, and who should skip it
I would recommend Dollarbird Pro to someone who repeatedly runs into timing problems: a bill is forgotten, a payday feels too far away, or a planned purchase collides with several commitments. It is also a good candidate for people who find spreadsheets too open-ended but want more foresight than a bank balance provides. The app has a clear identity, and that is helpful when the user’s problem is cash-flow visibility.
I would be more cautious for someone who wants automatic transaction imports, sophisticated category reports, debt payoff modeling, or investment tools. Those users may be better served by a specialized alternative, even if it has a steeper learning curve. I would also skip it if I know I will not enter future expenses. A calendar that is not maintained is worse than a simple account balance because it can look reassuring while being outdated.
For a first trial, I would create a realistic month rather than a perfect one. Include the ordinary bills, one irregular expense, and a few discretionary plans. Then check whether the calendar helps answer practical questions: Can I afford this purchase before the next income? Which week is tightest? What can move if the plan changes? If the answers come more quickly than they did before, the app is earning its place.
My final recommendation is therefore conditional but positive. Dollarbird Pro is not the universal answer to personal finance, and its middling 3.3 average means I would not ignore the possibility of friction. Still, its calendar-centered design solves a real problem that many expense trackers handle poorly. For people who need to see money in time rather than only in categories, the strongest reason to try it is its forward-looking view of everyday cash flow.
I would start with the free option, build one honest planning cycle, and judge the app by whether it improves decisions before spending. If I wanted reports and automation above all else, I would choose another category of tool. If I wanted a practical view of what is coming, and I was willing to keep the entries updated, I would give Dollarbird Pro a fair chance. It is a focused finance app, and its value comes from using that focus consistently rather than expecting it to replace every other money tool.
Dollarbird Pro FAQ
What is Dollarbird Pro and what can I use it for?
Dollarbird Pro is a personal finance and budgeting app designed to help you record income and expenses, organize transactions by category, and see how your balance may change over time. Its calendar-based approach makes it useful for planning recurring bills, subscriptions, and expected payments. It is aimed at people who want a clearer overview of daily spending and future cash flow rather than a full banking replacement.
Does Dollarbird Pro connect directly to my bank account?
Dollarbird Pro is primarily focused on manually managing financial information, so users should not assume that it automatically imports transactions from every bank or card provider. Depending on the version and platform, available synchronization features may vary. Before downloading, check the current store listing and privacy information to confirm whether bank connections, cloud synchronization, or account integrations are supported in your region.
Is Dollarbird Pro free to download, or does it require payment?
The availability and pricing of Dollarbird Pro can depend on the operating system, region, and the developer’s current subscription or purchase model. Some features may be included in the initial download while advanced tools, synchronization, or additional functionality may require payment. We recommend checking the Google Play or App Store listing carefully for the latest price, trial terms, and renewal conditions before installing.
Can I use Dollarbird Pro with a partner or family member?
Dollarbird Pro may be useful for shared household planning if its current version supports shared calendars, collaborative accounts, or synchronized data between users. However, collaboration features should not be assumed simply because the app is designed for budgeting. Review the latest feature list to confirm how many people can access a financial calendar, whether permissions are available, and how shared information is protected.
Is Dollarbird Pro safe for storing personal financial information?
As with any budgeting application, you should review Dollarbird Pro’s privacy policy and security details before entering sensitive information. Avoid storing bank passwords, card PINs, or unnecessary identity data unless the app clearly explains how that information is protected. A strong device passcode, updated operating system, and secure account password can provide additional protection, while regular backups help prevent accidental loss of your financial records.











